Personal Finance Tips: 12 Habits to Win With Money in 2026
These personal finance tips are the exact habits I wish someone had handed me a decade ago, before I learned every lesson the expensive way. Money mastery is rarely about a clever trick; it is about a handful of small routines repeated until they run on autopilot. In 2026, with inflation cooling but prices still elevated, the households that thrive are the ones that control the basics rather than chase get-rich schemes.
This guide walks through twelve practical habits, grouped so you can adopt them in order. None require a finance degree, and most take minutes to set up. Let us turn intention into a system that quietly grows your net worth.
Personal Finance Tips for Building a Foundation
Every stable financial life rests on the same few pillars. Skip them and even a high income leaks away; nail them and a modest salary stretches surprisingly far.
- Track every dollar for one month so you see the truth, not a guess.
- Build a starter emergency fund of $1,000, then grow it to three months of expenses.
- Pay yourself first by automating savings the day your paycheck lands.
- Keep fixed costs under 50% of take-home pay to preserve breathing room.
The emergency fund matters most. The Federal Reserve’s household survey has repeatedly found that a large share of Americans could not cover a sudden $400 expense with cash, and that single gap causes most debt spirals. Close it first and everything else gets easier.
Automate So Willpower Never Decides
Willpower is unreliable, but a scheduled transfer never forgets. Set an automatic move to savings for the same day your income arrives, even if it starts at $25. You will adjust to the smaller spendable balance within a month, and the fund grows without a single decision.
Smart Spending and Debt Habits
Once the foundation holds, direct your attention to leaks and liabilities. Small, consistent choices here free up hundreds of dollars a year that you can redirect toward goals.
- Wait 24 hours before any non-essential purchase over $50 to beat impulse buys.
- Attack high-interest debt first using the avalanche method to cut total interest paid.
- Audit subscriptions quarterly and cancel anything you have not used in a month.
- Use a low-cost payment app to split shared bills instead of fronting cash you forget to reclaim.
For everyday transfers and bill splitting, a well-run wallet keeps the process painless; this hands-on Cash App guide shows how to move money without the usual friction. Frictionless tools make good habits stick.
The Debt Payoff Order That Saves the Most
List every debt by interest rate, highest first. Pay the minimum on all of them, then throw every spare dollar at the top of the list. This avalanche approach mathematically minimizes what you hand to lenders, and watching the top balance vanish builds real momentum.
How Do You Grow Wealth on an Average Income?
This is the question I hear most, and the answer is refreshingly boring: invest early, invest consistently, and let compounding work. You do not need to time the market or pick the next hot stock. You need time and steady contributions.
| Habit | Monthly Effort | Long-Term Payoff |
|---|---|---|
| Automated savings | 5 minutes to set up | Full emergency fund |
| Employer 401(k) match | One enrollment form | Free instant return |
| Index fund investing | $50–$200 auto-buy | Compounding growth |
| Annual budget review | One hour a year | Plugged money leaks |
Capture your employer’s full 401(k) match before anything else, because it is a guaranteed return you will not find elsewhere. After that, a low-cost broad index fund on automatic monthly buys does the heavy lifting. Consistency beats brilliance over decades.
Protecting What You Build
Growing money means little if a single event wipes it out. Review your insurance coverage yearly and freeze your credit reports with the major bureaus to block identity theft. The U.S. Federal Trade Commission offers a free, step-by-step process for placing a credit freeze, and I consider it essential housekeeping.
A Simple Yearly Money Review
Once a year, block ninety minutes to give your finances a full checkup. Compare your net worth to last year’s figure, confirm your beneficiaries are current, and rebalance your investments back to your target mix. This annual ritual catches drift before it becomes a problem.
During the same session, shop your recurring bills. Insurance premiums, phone plans, and streaming bundles creep upward when nobody is watching, and a single phone call often reclaims real money. I have trimmed hundreds of dollars a year simply by asking providers for their current best rate.
Write down three concrete money goals for the year ahead and the automatic transfer that funds each one. Goals without a funded mechanism stay wishes, while goals wired to an automation quietly turn into results. Clarity plus automation is the whole game.
Layering a few extra personal finance tips around fraud prevention pays off, since one prevented scam can protect a year of savings. Treat your financial data with the same care you give your cash.
If your situation is complex, or you simply want a second set of eyes, dependable specialists can review your plan and flag blind spots. Good guidance early prevents costly corrections later.
Frequently Asked Questions
What is the most important personal finance tip?
Build an emergency fund first. Cash reserves keep an unexpected bill from turning into high-interest debt, which is the single biggest wealth destroyer for average households.
How much of my income should I save?
Aim for at least 20% of take-home pay split between savings and investments. If that feels impossible today, start with 5% and raise it one point each time you get a pay bump.
Should I pay off debt or invest first?
Capture any employer retirement match first, then attack high-interest debt above roughly 7%, and invest the rest. This order maximizes guaranteed and near-guaranteed returns.
Do I need a budgeting app to succeed?
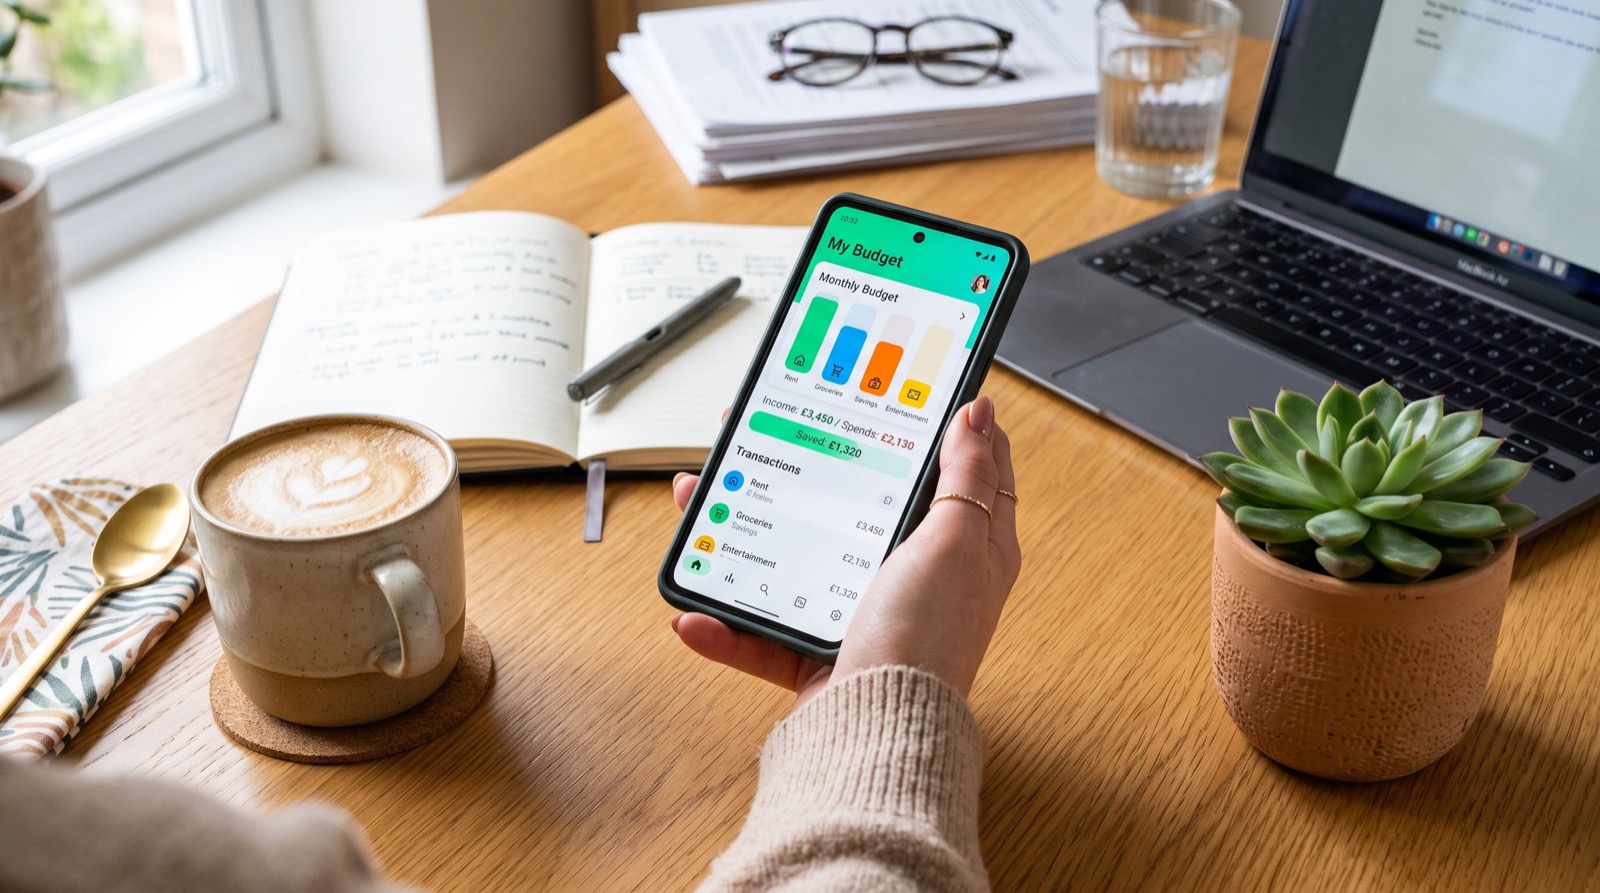
No, but it helps. An app automates tracking and alerts, yet a simple spreadsheet works too. The tool matters less than reviewing your numbers consistently.
Conclusion and Next Steps
Winning with money in 2026 does not require luck or a huge salary; it requires these personal finance tips practiced patiently until they become second nature. Start with an emergency fund, automate your savings, attack high-interest debt, and let index investing compound in the background. Each habit is small, but stacked together they change your financial trajectory.
Ready to begin? Pick just two habits from this list, set them up automatically this week, and revisit the rest once those first wins feel effortless.